
The short answer
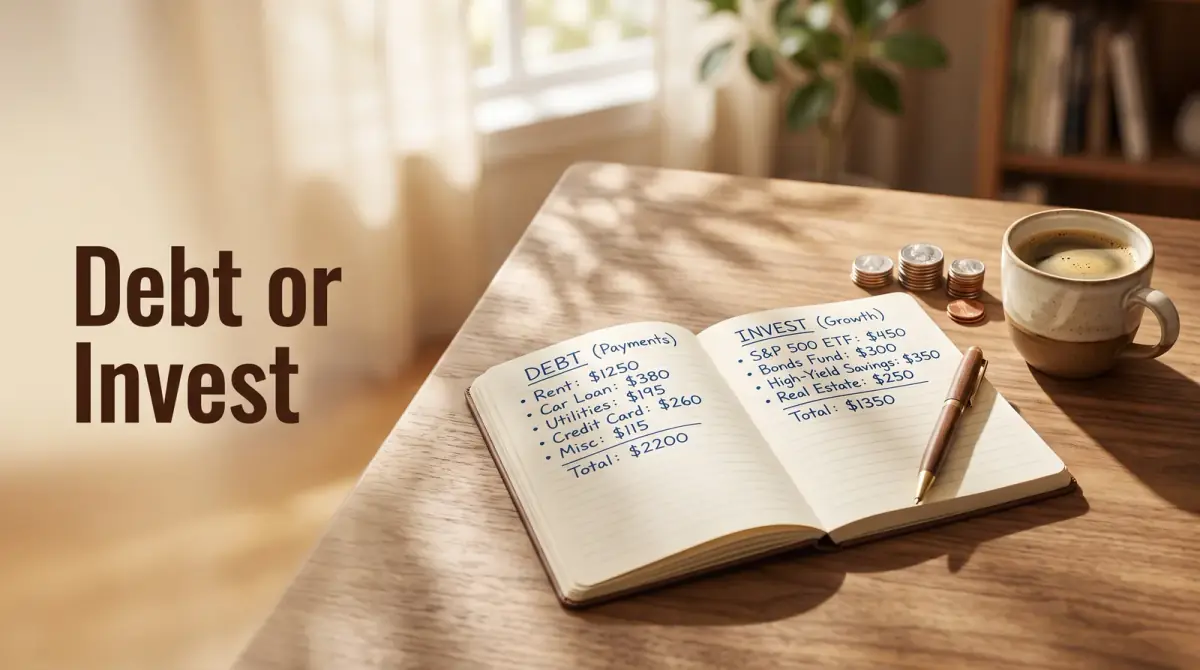
Extra cash and a nagging question: clear the loan or invest it? Should I get out of debt before investing depends on the numbers. Here is a simple way to decide.
- Compare your debt's interest rate to a realistic investing return.
- High-interest debt, like credit cards, usually wins the race for your money.
- Grab any free employer match first, since it is an instant return.
- Build a small emergency fund so you do not fall back into debt.
- Low-interest debt can often sit while you also invest.
Should you pay off debt before you invest? For most people, the answer comes down to comparing numbers. If your debt costs more in interest than you could reasonably expect to earn by investing, clear the expensive debt first. The one common exception is a free employer retirement match, which is usually worth grabbing before anything else. So the real answer to should I get out of debt before investing is "it depends on the interest rate," and this guide gives you a simple way to decide.
This is general education, not personal financial advice. Your situation is unique, and a qualified financial professional can help you apply these ideas.
Key takeaways
- Compare your debt's interest rate to a realistic investing return.
- High-interest debt, like credit cards, usually wins the race for your money.
- Grab any free employer match first, since it is an instant return.
- Build a small emergency fund so you do not fall back into debt.
- Low-interest debt can often sit while you also invest.
Start with the interest rate
The core of this decision is one comparison. On one side is the interest rate on your debt. On the other is the return you might realistically earn by investing.
Paying off a debt gives you a guaranteed return equal to its interest rate. Wipe out a card charging a high rate, and you have effectively "earned" that rate, risk-free. Investing, by contrast, offers no guarantee. Returns vary year to year and can be negative.
That is why the interest rate is your starting point. A guaranteed saving almost always beats an uncertain investment return of a similar size.
High-interest debt: pay it off first
Some debt is so expensive that clearing it is the best "investment" you can make. Credit cards and payday loans are the usual suspects.
When debt carries a high rate, it can grow faster than most investments realistically will. Trying to invest your way out while it piles up is like bailing a boat with a hole in it.
So if you are asking why get out of debt before investing, this is the heart of it. Expensive debt is a guaranteed drain, and stopping it is a guaranteed win. Knowing how to get out of debt like this usually means attacking the highest rate first.
Grab the free money first
There is one big exception to the "debt first" rule, and it is worth understanding.
If your employer offers to match your retirement contributions, that match is free money. A common setup adds money to your account for every dollar you put in, up to a limit. That is an immediate return you cannot get anywhere else.
For many people, the order looks like this:
- Contribute just enough to get the full employer match.
- Then throw everything extra at high-interest debt.
- Then return to investing more once the expensive debt is gone.
Skipping a full match to pay down a lower-rate debt often leaves money on the table.
Build a small safety net too
Before you funnel every spare dollar anywhere, set aside a small emergency fund. Even a modest cushion changes the game.
Without savings, one surprise bill can send you straight back to the credit card, undoing your progress. A starter fund keeps a bad week from becoming new debt.
Many people aim for a small starter amount first, then build a larger fund of several months of expenses over time. The right size depends on your job stability and family situation.
What about low-interest debt?
Not all debt is an emergency. Some loans carry low rates, and the math shifts for them.
When a debt's interest rate is low, a long-term investment might reasonably out-earn it over many years. In that case, some people choose to invest while making steady payments on the cheap debt, rather than rushing to clear it.
There is a catch worth naming. This is a math argument, not a feelings argument. Some people sleep better with zero debt, whatever the spreadsheet says. That peace of mind is a real and valid reason to get out of debt faster.
Should I get out of debt before investing? A framework
Put it together and you get a rough order of priority. Adjust it to your own life.
- Get the full employer match if one is offered.
- Build a small emergency fund so setbacks do not create new debt.
- Attack high-interest debt hard, starting with the highest rate.
- Then invest more and treat any low-interest debt as optional to rush.
This is why the answer to should I get out of debt before investing is rarely all-or-nothing. Most people do a bit of both, in a sensible order.
A simple way to picture the choice
Imagine two people with the same spare money each month. One has credit card debt at a high rate. The other has only a low-rate loan.
For the first person, paying down that card is like earning a high, guaranteed return. Almost no investment can promise that, so clearing the debt usually wins.
For the second person, the cheap loan is not urgent. They might comfortably invest while paying it off slowly, since a long-term investment could reasonably do better over many years.
Same habit, different answer, and the interest rate is what flips it. This is why a blanket rule rarely fits everyone.
What if you have several debts?
Many people juggle more than one balance at once. Two popular ways to tackle them can both work.
- Pay the highest interest rate first to save the most money over time.
- Or pay the smallest balance first for a quick, motivating win.
The math tends to favor the first approach. Motivation sometimes favors the second. The best method is the one you will actually stick with.
Questions to ask yourself
Numbers matter, but so does your life. Run through these before you decide.
- What is the exact interest rate on each debt I owe?
- Am I leaving any free employer match on the table?
- Do I have a cushion for a surprise expense?
- Would carrying debt keep me up at night?
- How stable is my income right now?
There is no single right answer for everyone. The goal is a plan that fits both the math and how you actually feel about risk.
The bottom line
So, should you get out of debt before investing? Clear the expensive debt first, grab any free match along the way, and keep a small safety net so you do not slide backward.
Once the costly debt is gone, investing gets much easier, because your money is working for you instead of for a lender. If the numbers feel hard to weigh, a qualified financial professional can help you build a plan around your real situation.
Comments
0 total