
The short answer
A practical guide to retirement planning for millennials, covering compound growth, smart accounts, and simple steps to build wealth over time.
- Employer-sponsored plans let you contribute directly from your paycheck, often with a match.
- Individual retirement accounts offer tax benefits and a wide range of investment choices.
- Tax-advantaged options can reduce what you owe now or let your money grow tax-free later.
Retirement planning for millennials comes down to one powerful advantage: time. Starting early, even with small amounts, lets compound growth do the heavy lifting over decades. You don't need a huge salary or a complex strategy to build real wealth. You need to begin now and stay consistent.
Many millennials feel retirement is impossibly far away or financially out of reach amid student loans, rising costs, and uncertain job markets. The truth is more hopeful. With a clear plan and long time horizons on your side, your generation is in a strong position to retire comfortably. Here's how to get started.
Why Should Millennials Start Retirement Planning Now?
The single biggest factor in retirement savings isn't how much you earn; it's how early you start. Compound growth means your money earns returns, and then those returns earn returns too. Over thirty or forty years, that snowball effect becomes enormous.
A modest amount invested in your twenties can outgrow a much larger amount invested in your forties, simply because it had more time to compound. Waiting even a few years can cost you significantly in the long run. Time is the one advantage you can't get back.
How Much Should You Save for Retirement?
There's no single magic number, but a common guideline is to aim to save a meaningful percentage of your income each year, often suggested around 15% including any employer contributions. If that feels impossible today, start with what you can and increase it over time.
Start Small and Scale Up
Don't let perfect be the enemy of good. Begin with a percentage you can sustain, even if it's small. Getting started matters far more than starting big. Each time you get a raise, direct part of it toward savings before you adjust your lifestyle.
Take the Free Money First
If your employer offers a retirement match, contribute at least enough to capture the full match. That match is essentially free money and an instant return on your contribution. Skipping it leaves guaranteed value on the table.
Which Accounts Should Millennials Use?
Choosing the right accounts helps your money grow more efficiently, often with tax advantages. The specifics vary by country, but the principles are similar.
- Employer-sponsored plans let you contribute directly from your paycheck, often with a match.
- Individual retirement accounts offer tax benefits and a wide range of investment choices.
- Tax-advantaged options can reduce what you owe now or let your money grow tax-free later.
A common approach is to contribute enough to capture any employer match first, then fund an individual retirement account, then return to maxing out your workplace plan. Consider speaking with a qualified financial professional for advice tailored to your situation.
How Should You Invest for the Long Term?
Saving is only half the equation. Where you put that money determines how much it grows.
Embrace Time and Stay Invested
Because you have decades ahead, you can generally afford to invest for growth and ride out the market's inevitable ups and downs. Trying to time the market usually backfires. Staying invested consistently tends to beat jumping in and out.
Keep Costs Low and Diversify
High fees quietly erode your returns over time. Many experts favor low-cost, broadly diversified funds that spread your money across many companies. Diversification reduces the risk of any single investment sinking your plan.
Match Risk to Your Timeline
The further you are from retirement, the more time you have to recover from downturns, which is why younger investors can generally lean toward growth. As you approach retirement, many people gradually shift toward more stable holdings to protect what they've built. Your ideal mix should evolve as your timeline shortens.
Automate Everything
Set up automatic contributions so investing happens without you thinking about it. Automation removes the temptation to skip a month and turns saving into an effortless habit. What you automate, you don't have to negotiate with yourself.
What Common Mistakes Should You Avoid?
Steer clear of these traps that derail many young savers.
- Waiting to start. Every year you delay is a year of lost compounding.
- Cashing out early. Withdrawing retirement funds when changing jobs can trigger penalties and reset your progress.
- Lifestyle inflation. Letting spending rise with every raise leaves nothing extra to invest.
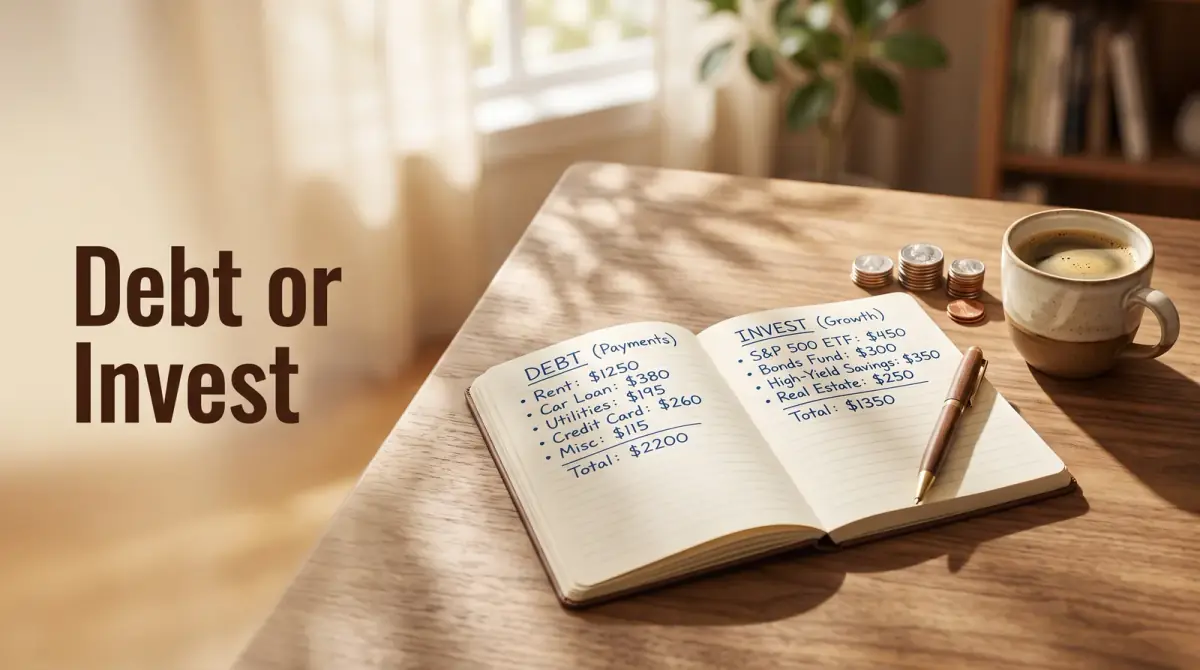
- Ignoring debt strategy. High-interest debt can outweigh investment gains, so balance paying it down with saving.
- Panic selling. Selling during downturns locks in losses and misses the recovery.
Building a Realistic Millennial Retirement Plan
Here's a simple framework to put it all together.
- Build a small emergency fund so you won't raid your investments for surprises.
- Capture your full employer match to grab free money.
- Tackle high-interest debt while continuing to save something.
- Automate steady contributions into diversified, low-cost investments.
- Increase your savings rate gradually as your income grows.
- Review annually and adjust as your life and goals evolve.
The Bottom Line
Retirement may feel distant, but the choices you make in your twenties and thirties will shape it more than anything you do later. You have the most valuable asset in investing on your side right now: time. Even small, consistent steps today can grow into lasting financial freedom.
Don't wait for the perfect moment or the perfect paycheck. Open an account, automate a contribution, and let compounding work in your favor. Future you will be deeply grateful you started.
The best time to start planning for retirement was yesterday. The second-best time is today.
Comments
0 total