The short answer
Compounding is not slow, it is back-loaded. Here is the mechanism, why the early years feel pointless, and how the same curve works against you in debt.
- Year 1 earns $700, ending at $10,700.
- Year 2 earns $749, ending at $11,449.
- Year 3 earns about $801, ending at roughly $12,250.
You put money away for three years and it barely moves. You check the balance, run the mental math, and quietly conclude the whole thing is a scam. That reaction is the single biggest reason people quit early, and it is exactly why understanding how compound interest works matters more than picking the perfect account.
Compounding is not slow. It is back-loaded. Those are very different problems, and only one of them has a fix.
How compound interest works, in one sentence
Compound interest means your growth starts earning growth of its own. Simple interest pays you on what you originally put in. Compound interest pays you on what you put in plus everything it has already earned.
Take a hypothetical. You park $10,000 somewhere that returns 7% a year, purely as an illustration of the shape of the math.
- Year 1 earns $700, ending at $10,700.
- Year 2 earns $749, ending at $11,449.
- Year 3 earns about $801, ending at roughly $12,250.
Nothing dramatic. But notice the earnings themselves are climbing: $700, then $749, then $801. You did not add a cent. The engine got bigger, so it produces more on each pass. Run that loop long enough and the increases stop being small.
Why does compounding feel like nothing for years?
Because early on, almost all of your balance is money you deposited yourself. The growth has not had time to become a meaningful share of the pile. You are essentially watching a savings account with a slight tailwind.
Keep going with that same hypothetical $10,000 at 7%:
- After 10 years: about $19,700
- After 20 years: about $38,700
- After 30 years: about $76,100
- After 40 years: about $149,700
Now look at what each decade adds. The first adds under $10,000. The second adds around $19,000. The third adds roughly $37,000. The fourth adds about $74,000, which is more than seven times what the first decade produced, from the exact same deposit and the exact same rate.
Compounding does not reward you for being clever. It rewards you for still being there.
The rule of 72 makes it visible
Divide 72 by your annual growth rate and you get a rough number of years for money to double. At a hypothetical 7%, that is a little over ten years per doubling.
Here is the part people miss. The final doubling adds as much money as every doubling before it put together. Going from $75,000 to $150,000 hands you another $75,000 in one stretch, matching the entire climb from zero to $75,000 - except this time almost none of it came out of your pocket. That last stretch is where the whole thing pays off, and it is the stretch most people never reach, because they bailed during the boring part.
Does time matter more than the amount?
Usually yes, and the gap is wider than it sounds. Here is a hypothetical worth sitting with. Two people, same assumed 7% return.
- Person A saves $2,400 a year for ten years, then stops completely and never adds another dollar. Total contributed: $24,000.
- Person B starts ten years later and saves $2,400 a year for the next thirty years. Total contributed: $72,000.
Forty years from the start, Person A is sitting on roughly $252,000. Person B, who put in three times as much money, has roughly $227,000.
Person A won by quitting early. That is not a typo. Their money simply ran through more doublings. Early dollars are structurally worth more than later dollars, and no amount of catching up fully closes that gap.
This is not a reason to despair if you are starting late. It is a reason to start this month rather than next year, and to stop waiting until you can contribute an impressive amount. A small sum that has been running for years beats a large sum that starts eventually.
How does compound interest work against you?
Same curve, pointed at your face. Debt compounds too, and it usually compounds harder than anything on the savings side, because the rate tends to be higher and the compounding period is often monthly rather than yearly.
Hypothetically: a $5,000 balance at a 20% annual rate, compounding monthly, with no payments at all. After twelve months you would owe roughly $6,100. You bought nothing new. The balance grew because interest got added to the balance and then started earning interest itself.
Why minimum payments feel like quicksand
A minimum payment is typically sized to cover the interest plus a sliver of principal. That keeps the account current and keeps the balance nearly intact. You can pay faithfully every month for years and watch the number barely move, which feels exactly like the early years of saving, except the curve is running the other way.
- Anything above the minimum goes straight at the principal, which shrinks the engine.
- Paying down high-rate debt is a guaranteed return equal to that rate. Very little on the investing side is guaranteed.
- If you are carrying high-rate debt while saving, the debt is almost certainly compounding faster than the savings.
What quietly kills compounding?
Three things, and none of them announce themselves.
Gaps. Stopping contributions for a year does not just cost you that year's deposit. It costs every doubling that deposit would have gone through afterwards. The cheapest year to contribute is always the earliest one available.
Withdrawals. Dipping into long-term money resets the engine to a smaller size, permanently. This is the real argument for an emergency fund: it is not about the interest it earns, it is about protecting the thing that is actually compounding.
Costs. Fees compound too. A percentage skimmed off every year is subtracted from the growth rate itself, which is the input the whole curve is built on. Small percentages sound trivial and are not, precisely because they get applied to a balance that is meant to be getting bigger.
Notice that all three are behaviour, not market performance. You cannot control the returns you get. You have quite a lot of control over these.
How do you put compounding on your side?
- Start before you feel ready. The first contribution buys time, and time is the one input you cannot manufacture later.
- Automate it. Compounding punishes gaps. A transfer that happens without a decision survives your bad months.
- Leave the growth in. Pulling out earnings resets the engine to a smaller size. Reinvesting is the entire mechanism.
- Raise contributions when your income rises, before your spending absorbs it. This is the least painful increase you will ever make.
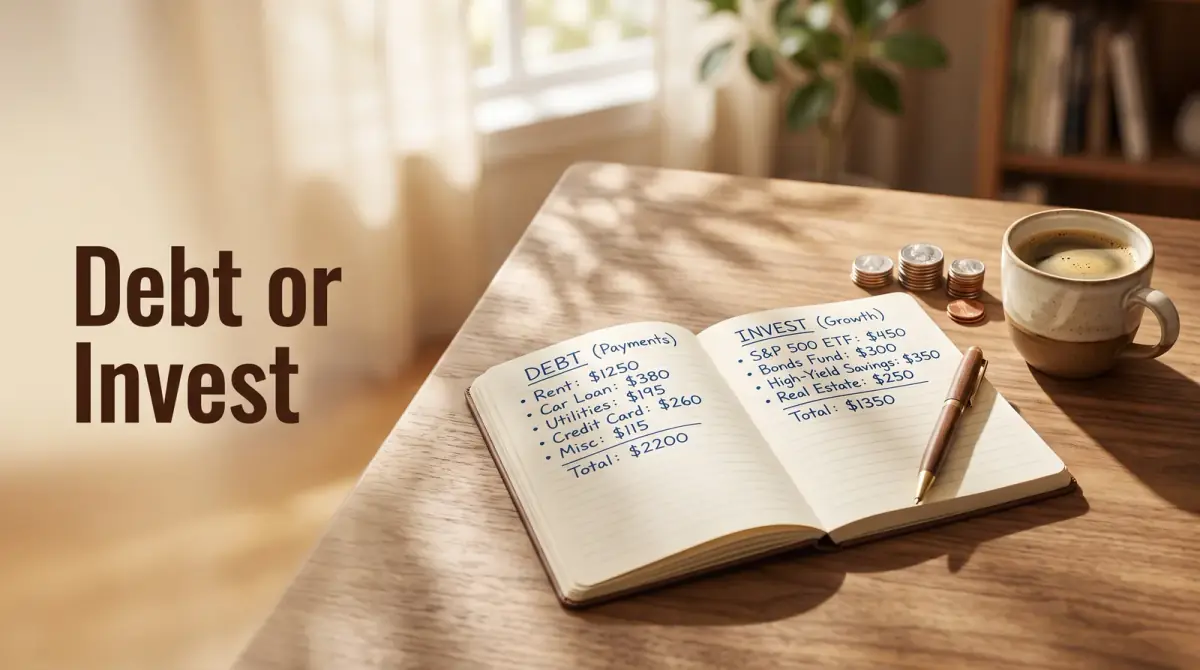
- Kill high-rate debt first. There is no sense feeding one curve while another one eats you faster.
- Check the balance less often. Frequent checking makes a back-loaded process feel broken when it is working fine.
The takeaway
Compounding is a patience machine with a delayed payout. The years that feel pointless are not wasted; they are the setup for the years that do the heavy lifting. Nothing much happens for a long time, and then a lot happens quickly.
Your move this week is small. Set up one automatic transfer at an amount you will not miss, and then leave it alone. If you are carrying expensive debt, point that same automation at the debt first.
Every figure above is a hypothetical chosen to show the shape of the math, not a prediction. Real returns bounce around, and rates and tax treatment vary by country and product. The mechanism, though, does not change.
Comments
0 total