
The short answer
A score can slip without warning. Here are the common reasons why credit score decrease happens, from missed payments to new inquiries, and how to recover.
- Most drops trace back to one change, like a late payment or a higher balance.
- New applications, closed accounts, and errors can all pull a score down.
- A blank score is often about thin data, not a penalty.
- Steady habits are what turn a decrease back into an increase.
- Big or unexplained drops are worth checking with a professional.
If your score just fell, the usual culprits are a missed or late payment, a rise in how much of your credit you are using, or a new application for credit. In most cases the drop reflects one specific change on your report, not a mystery. Understanding why credit score decrease happens makes the number far less scary and much easier to fix.
Some dips are temporary and bounce back on their own. Others need a small course correction. Either way, it usually has a clear cause once you know where to look.
Key takeaways
- Most drops trace back to one change, like a late payment or a higher balance.
- New applications, closed accounts, and errors can all pull a score down.
- A blank score is often about thin data, not a penalty.
- Steady habits are what turn a decrease back into an increase.
- Big or unexplained drops are worth checking with a professional.
Why credit score decrease happens: the usual suspects
Scores move as new information lands on your credit report. When the number falls, one of the following is usually behind it.
A missed or late payment
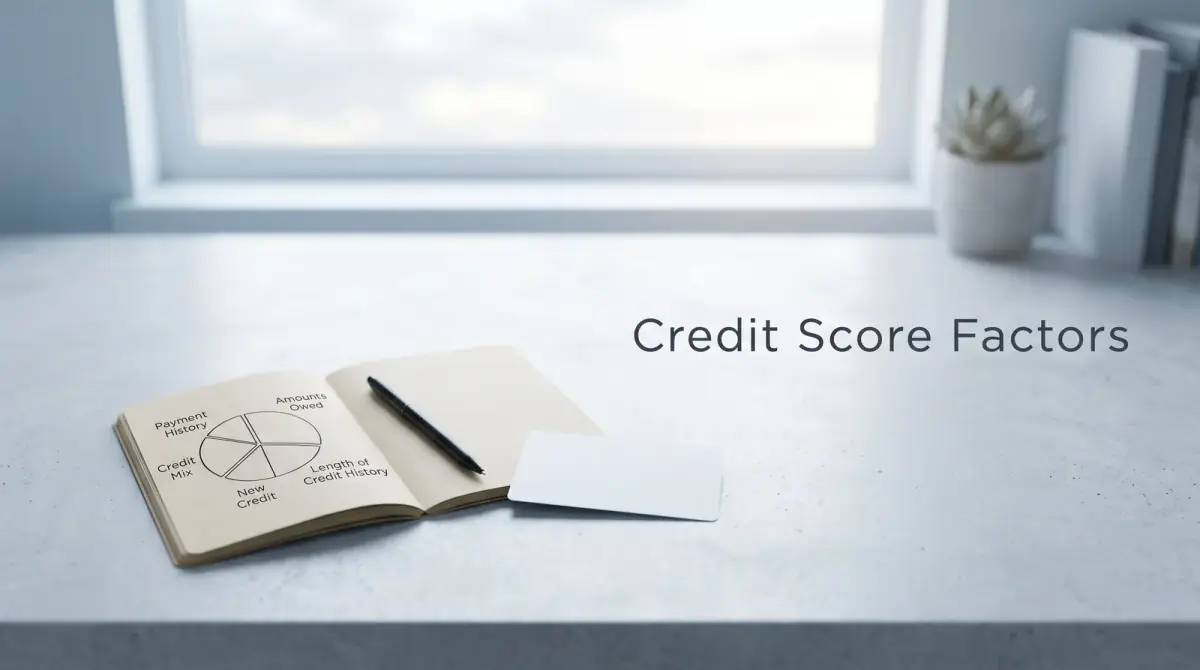
Payment history is the heaviest factor in how credit score is calculated, so a single late payment can pull the number down more than people expect. Even a bill you forgot for a few days can leave a mark once it is reported.
Your balances went up
Credit utilisation is the share of your available credit you are using. If you charged a big purchase, your balances climbed, and your utilisation jumped, your score can dip even if you always pay on time. This is one of the most common reasons for a sudden drop.
You applied for new credit
Applying for a card or loan can trigger a hard inquiry, which may shave a few points. One is minor. Several in a short window can look like financial stress and hit harder.
You closed an old account
Closing a card removes its limit from your total available credit, which can raise your utilisation overnight. It can also shorten your average account age. Both can nudge a score down, even though closing felt like a tidy move.
An error on your report
Sometimes the drop is not your doing at all. A payment logged as late by mistake, an account that is not yours, or old debt that should have aged off can all drag the number down.
A lender lowered your limit
Your utilisation depends on your total available credit, so it can rise even when your spending stays flat. If a lender cuts one of your credit limits, the same balance now takes up a bigger share of what is available, and your score can dip as a result.
The drop that is not really a drop
Not every change is a true decline. Scores from different providers use different formulas, so the figure your bank shows may not match the one a lender pulls. Comparing two different models can make it look like your score fell when nothing real changed.
Timing matters too. Your score is a snapshot from a specific day. If you checked right after a big purchase but before you paid the balance, the number reflects that moment, not your overall habits.
Why credit score is not showing at all
Sometimes the worry is not a lower number but a missing one. If you are wondering why credit score is not showing, the reason is usually thin or stale data rather than a penalty.
- You are new to credit and do not have enough history yet to generate a score.
- You have not used any credit accounts recently, so there is little fresh activity to score.
- Your accounts are not being reported to the bureau your provider checks.
- Your personal details do not match the file, so the record cannot be found.
A blank score is not the same as a bad one. It usually means the system does not have enough to work with yet, and steady, on-time activity fills that gap over time.
How to recover and turn it around
The good news is that the same factors that caused the dip can lift it again. A credit score increase tends to follow a few steady moves rather than one dramatic fix.
- Bring any late accounts current and keep every future payment on time.
- Pay balances down so your utilisation drops well below your limits.
- Pause new applications for a while so no fresh inquiries pile up.
- Keep older accounts open when it makes sense, to protect your history.
- Check your report and dispute anything that looks wrong.
Recovery is rarely instant. Because scores update as new data arrives, give any good habit a few billing cycles to show up. Results vary, and someone repairing a serious miss may take longer than someone clearing a small blip.
It also helps to fix the biggest lever first. Since payment history and utilisation carry the most weight in how credit score is calculated, getting current and lowering balances usually moves the number faster than chasing small factors. Do not open new accounts just to pad your credit mix, since the new inquiry can cost you in the short term.
How long does the drop last?
How long a dip sticks around depends on what caused it. A high balance you pay down can recover within a billing cycle or two, once the lower figure reaches your report. A single late payment fades more slowly, because payment history weighs so heavily and the record can linger.
More serious marks, like a default or an account sent to collections, take the longest to move past. The general pattern is that recent negative events hurt the most and matter less as time passes and you build a fresh run of good behaviour. Time plus steady habits is the combination that works.
When to get help
A few points here and there are normal, and scores wobble naturally month to month. But some situations deserve a closer look.
If your score falls sharply with no clear reason, if you spot accounts you never opened, or if debt is starting to feel unmanageable, it is worth acting. This article is general information, not personal financial advice. A qualified credit counsellor or financial adviser can review your report, help you challenge errors, and build a plan that fits your situation.
Above all, do not panic at a single dip. Once you know why credit score decrease happens, most drops turn out to be explainable, fixable, and temporary.
Comments
0 total