
The short answer
Wondering what credit score is good? Here is how the ranges work, what lenders treat as good or excellent, and the everyday habits that move your number up.
- Good usually starts in the 700s. Most models treat the low 700s and up as good credit.
- Excellent is the 800s. The top band unlocks the best rates lenders offer.
- Ranges vary by model. The exact number that counts as good depends on which score a lender pulls.
- Habits matter more than the exact digit. Paying on time and keeping balances low move your score the right way.
If you are wondering what credit score is good, here is the short answer: on the scoring models most lenders use, a score in the low-to-mid 700s or higher is widely treated as good, and scores in the 800s are usually called excellent. A good score tells a lender you are likely to repay what you borrow, which often means easier approvals and lower interest rates.
The catch is that there is no single official cutoff. Different scoring models draw the line in slightly different places, so it helps to understand the ranges rather than chase one magic number.
Quick answer: the key takeaways
- Good usually starts in the 700s. Most models treat the low 700s and up as good credit.
- Excellent is the 800s. The top band unlocks the best rates lenders offer.
- Ranges vary by model. The exact number that counts as good depends on which score a lender pulls.
- Habits matter more than the exact digit. Paying on time and keeping balances low move your score the right way.
So what credit score is good, exactly?
The two most common models, FICO and VantageScore, both run on a scale of 300 to 850. On that scale, higher is better, and the commonly used bands look roughly like this:
- Poor: around 300 to 579
- Fair: around 580 to 669
- Good: around 670 to 739
- Very good: around 740 to 799
- Excellent: around 800 to 850
So when people ask what credit score is considered good, the honest reply is anything from the high 600s upward, with each step higher opening slightly better terms. Treat these bands as guidelines, not hard rules, because lenders set their own standards.
How credit score ranges work across models
You do not have just one credit score. You have several, because different companies build different models from the same underlying credit reports.
FICO and VantageScore are the best known, and they often land close to each other. But they weigh some details differently, so your FICO score and your VantageScore may not match exactly. Lenders in different industries, like mortgage or auto lending, sometimes use specialized versions too.
The practical takeaway is simple. Do not panic if two apps show slightly different numbers. Watch the general range and the trend over time instead of obsessing over a five-point gap.
What lenders actually treat as good
Your score is one input, not the whole decision. A lender also looks at your income, how much debt you already carry, and how much you are asking to borrow.
That said, the band you fall into shapes the offers you see:
- Fair credit may get you approved, but often with higher rates or a required deposit.
- Good credit tends to unlock mainstream rates and a wider choice of cards and loans.
- Very good or excellent credit usually earns the lowest advertised rates and the strongest rewards offers.
The difference between good and excellent can be real money over the life of a loan, which is why nudging your score upward is worth the effort.
How credit score is calculated
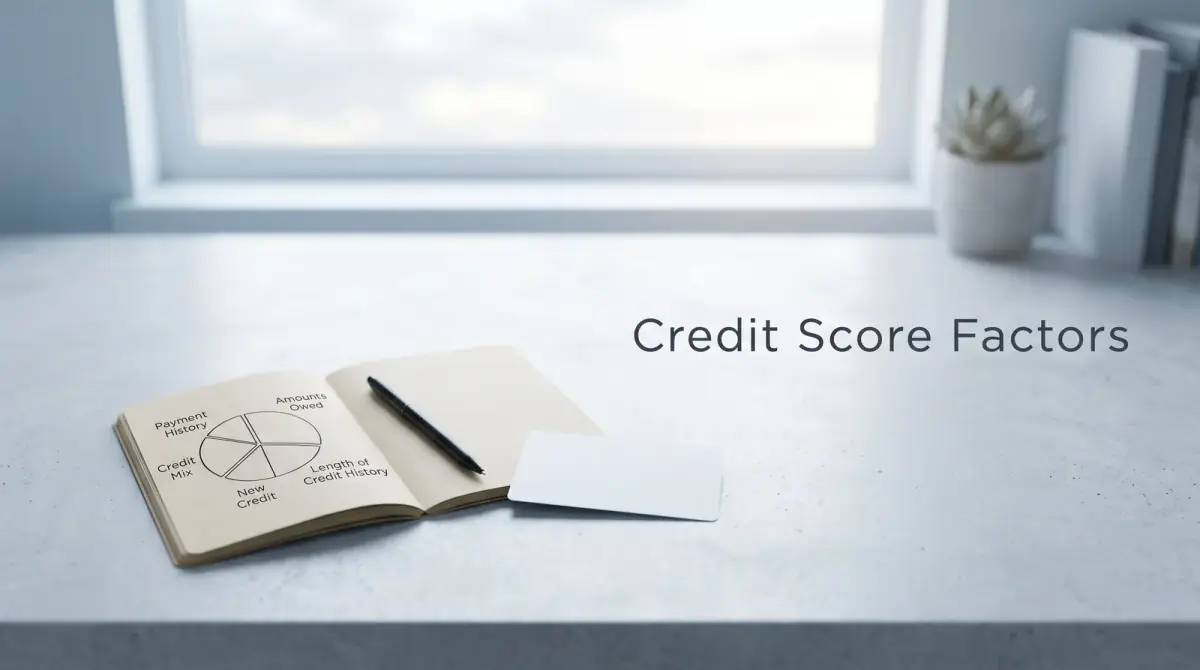
Understanding how credit score is calculated makes it far easier to improve yours. Most models draw on a handful of factors, and while the exact math is private, the general weightings are well known.
Payment history
This is the single biggest factor for most people. Paying bills on time, every time, is the most powerful thing you can do. A single missed payment can sting, and late marks can linger on your report for years.
Amounts owed and credit utilization
Utilization is how much of your available credit you are using. If your card limit is 1,000 and you carry a 900 balance, that is very high usage. Keeping balances low relative to your limits generally helps your score.
Length of credit history
A longer track record gives models more to work with. This is why closing your oldest card can sometimes backfire.
New credit and credit mix
Opening several accounts in a short window can look risky. Having a healthy mix of account types, handled responsibly, can help a little. These factors matter less than payment history and utilization, but they still count.
Habits that move your number the right way
You cannot flip your score overnight, but steady habits add up. Here is where to focus:
- Pay on time, always. Set autopay for at least the minimum so a busy week never costs you.
- Keep balances low. Aim to use a small share of your available credit, and pay down cards before the statement closes when you can.
- Avoid opening a lot of accounts at once. Space out applications so you do not stack up hard inquiries.
- Keep old accounts open. Length of history helps, so think twice before closing a long-held card.
- Check your reports for errors. Mistakes happen, and disputing an error can lift a score that was dragged down unfairly.
Your score rewards consistency. A boring, on-time payment record beats any quick trick.
What counts as the best credit score?
Technically the best credit score is 850, the top of the common scale. But chasing a perfect number is not worth the stress. Once you are comfortably in the very good or excellent band, you already qualify for the best rates most lenders offer.
In other words, going from 760 to 800 rarely changes your real-world offers much. Getting from 640 to 720 usually changes them a lot. Effort is best spent climbing out of the lower bands, not polishing an already strong score.
Common questions
Does checking my own score hurt it? No. Checking your own score is a soft inquiry and does not affect it. Only certain lender pulls, called hard inquiries, can nudge it down slightly.
How fast can I improve? It varies. Some habits, like lowering utilization, can show up within a billing cycle or two. Rebuilding after serious damage takes longer and rewards patience.
What if I have no score at all? Having no credit history is different from bad credit. Responsibly using a starter card or a credit-builder product over time can help you establish a record.
So, what credit score is good? Anything from the high 600s and up puts you in solid territory, and the 700s or better opens the friendliest terms. Focus less on the exact digit and more on the habits behind it. Pay on time, keep balances low, and let time do the rest, and a good score tends to follow.
Comments
0 total