
The short answer
Your credit score comes from a formula that weighs a few key factors. See how credit score is calculated, which parts matter most, and where to focus first.
- Your score comes from your credit report, not your bank balance or income.
- Payment history and credit use carry the most weight in most models.
- Length of history, new applications, and credit mix play smaller roles.
- Scores can differ between providers because they use different formulas.
- Steady, on-time habits move a score more than any quick trick.
Your credit score is calculated from the information in your credit report, run through a scoring formula that weighs a handful of factors. The two that count most are your payment history and how much of your available credit you use. Once you understand how credit score is calculated, it gets much easier to see where your effort actually pays off.
No single detail defines you, and no one factor tells the whole story. The score is really a snapshot of how you have handled borrowing over time.
Key takeaways
- Your score comes from your credit report, not your bank balance or income.
- Payment history and credit use carry the most weight in most models.
- Length of history, new applications, and credit mix play smaller roles.
- Scores can differ between providers because they use different formulas.
- Steady, on-time habits move a score more than any quick trick.
What a credit score actually measures
A credit score is a number that sums up how likely you are to repay borrowed money on time. Lenders use it as a fast read on risk when you apply for a card, loan, or mortgage.
It is built only from your credit behaviour. Your salary, savings, age, and job are not part of the score itself, even though a lender may look at those things separately when you apply. Think of the score as your borrowing reputation, packed into a single number.
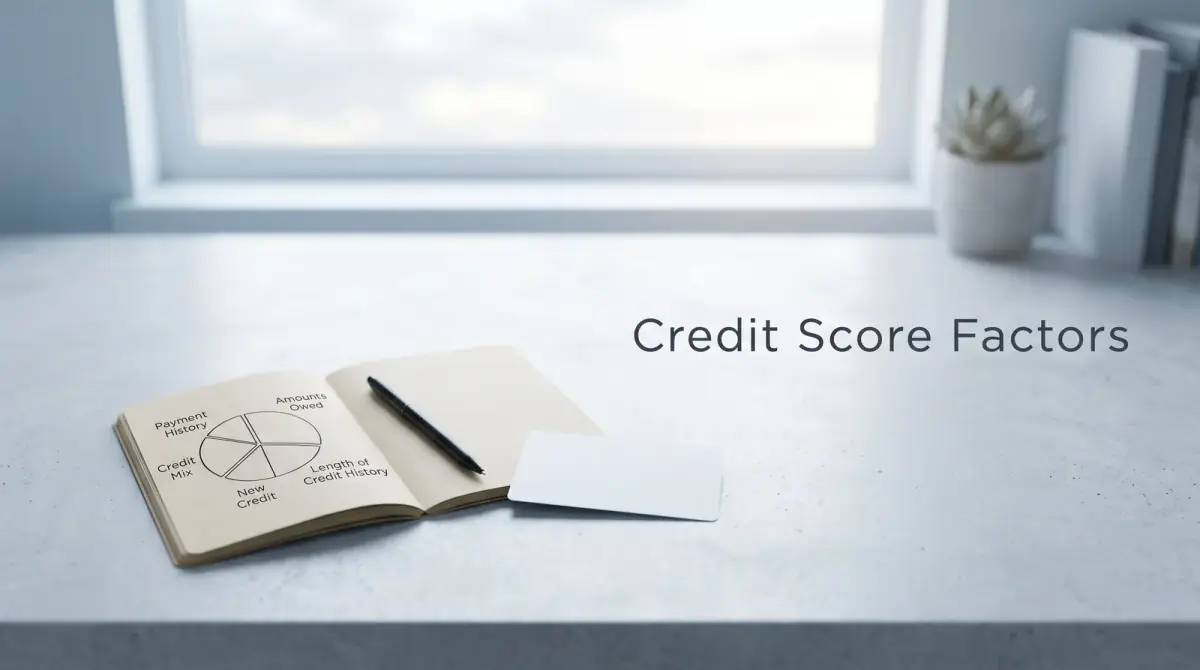
How credit score is calculated: the main factors
Different companies use different formulas, but most look at the same core areas. Here is what usually goes into the mix, from the heaviest factor to the lightest.
Payment history
This is your track record of paying on time. Late payments, defaults, and accounts sent to collections drag it down. A long run of on-time payments builds it up. In most models this is the single biggest factor, which is why one missed bill can sting more than people expect.
Amounts owed and credit use
This looks at how much you owe, and especially your credit utilisation. That is the share of your available credit you are actually using. Say a card has a limit of 1,000 and you owe 300 on it. That is 30 percent utilisation. Being close to your limit signals strain, so keeping balances well below the limit usually helps.
Length of credit history
A longer history gives the formula more to work with. The age of your oldest account and the average age of all your accounts both play a part. This is one reason closing an old card can sometimes backfire, since it can shorten your average account age.
New credit and applications
Each time you apply for credit, a hard inquiry may be recorded. Several close together can look like you are scrambling for cash. One application now and then is completely normal and has only a small effect.
Credit mix
Having a range of credit types, such as a card alongside an installment loan, can help a little. It is a minor factor, so it is never worth taking on debt you do not need just to add variety.
Which factors carry the most weight
Not every factor counts the same. In the scoring models most people run into, the order of importance usually looks like this:
- Payment history, the largest slice.
- Amounts owed and utilisation, a close second.
- Length of credit history.
- New credit and credit mix, the smallest pieces.
The exact weightings vary by provider and by country, so treat this as a guide rather than a fixed rule. The practical message is simple. Pay on time and keep balances low, and you are already handling the two things that matter most.
What credit score is good?
People often ask what credit score is good, and the honest answer is that it depends on the scale. Different providers use different ranges, so a number that looks high on one scale might sit in the middle on another.
Rather than chase one magic figure, aim for the upper end of whatever range your provider uses. Higher scores tend to unlock better interest rates and easier approvals. Check which model your lender relies on so you are comparing like with like, not a score from one company against a range from another.
How credit score increase and decrease happen
Once you know how the pieces fit together, movement in your score starts to make sense. A credit score increase usually comes from the same unglamorous habits repeated over months: paying every bill on time, paying down balances, and letting your accounts quietly age.
A credit score decrease tends to come from the opposite. Why credit score decrease happens most often is a missed payment, a sudden jump in your balances, or a burst of new applications in a short window. Because payment history carries so much weight, a single late payment can have an outsized effect.
Change is rarely instant. Scores update as new information reaches your report, so give any good habit a few billing cycles to show up. Results vary from person to person, and someone rebuilding after a rough patch may see slower progress than someone with a small blemish to clear.
A few things the score does not care about
It also helps to clear up some common myths, because chasing the wrong fixes wastes energy.
- Checking your own score does not lower it. That is a soft check and is safe to do often.
- Carrying a balance for its own sake does not help. Paying in full is fine.
- Your income is not baked into the score, even if lenders look at it separately.
- Closing every card is not automatically smart, since it can raise your utilisation.
Keep an eye on it, and get help if you need it
Check your credit report now and then for mistakes, because errors can drag a score down through no fault of yours. Many providers let you view your score for free, and reviewing it a couple of times a year is a healthy habit.
This article is general information, not personal financial advice. If debt is starting to feel unmanageable, or your report shows accounts you do not recognise, a qualified credit counsellor or financial adviser can help you work out the right next steps for your situation.
Comments
0 total